Ho Chi Minh City Condo Prices Q3 2026: Primary Price Falls to VND 75 Million/m² as New Supply Halves
Short answer: In Q3 2026 the Ho Chi Minh City apartment market slowed sharply. New launches fell 50% and units sold fell 71% year on year, the average primary price slipped to VND 75 million/m² (-14%), and mortgage rates stayed near 10.6% even as nine-month GDP grew 9.01%. Hanoi is weak too, but its primary price is still VND 86 million/m². Landed property split: HCMC sold more (+226%) at lower prices, while Hanoi’s primary price rose 33% on slow sales.
The figures come from CBRE Vietnam’s Q3 2026 Vietnam Real Estate Market Insights (October 2026). Realtique reads them from the point of view of a buyer of an HCMC apartment, redraws the charts and flags where the numbers cannot be compared: from 2026, “HCMC” in CBRE’s statistics includes Binh Duong and Ba Ria – Vung Tau. These are asking prices, not transaction prices after discounts.
Apartment Market Q3 2026 — 4 Key Numbers
Table of Contents
Macro: The Fastest Growth in 15 Years, but Mortgage Rates Stay Above 10%
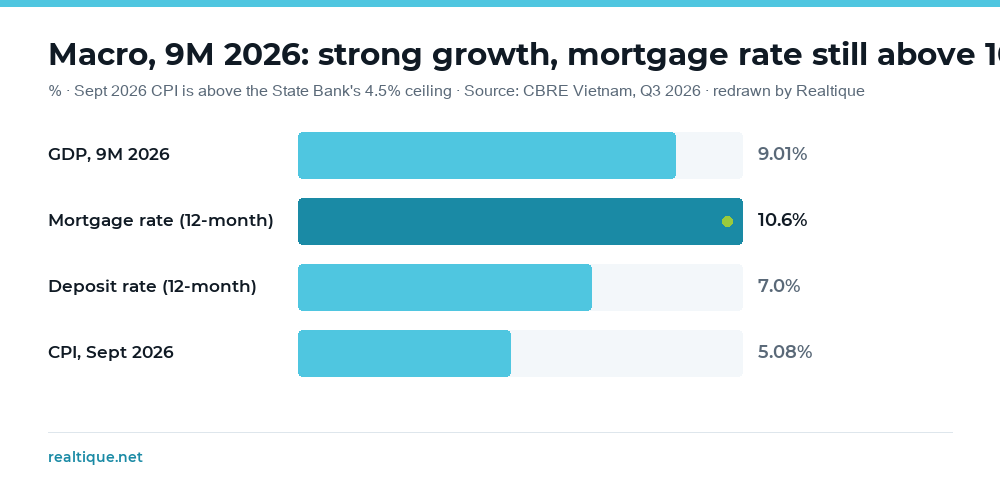
GDP grew 9.01% in the first nine months of 2026, the highest in 15 years and well above the 7.85% of the same period in 2025. The ADB also raised its 2026 growth forecast for Vietnam from 7.2% (July) to 7.8% (September), the highest in Southeast Asia. Foreign capital accelerated: registered FDI for nine months rose 76.4% year on year and already exceeds the full-year 2025 total by about 31%; Singapore (31.7%), Korea (19.5%) and Luxembourg (17.1%) are the three largest sources of newly registered capital.
For housing, the bottleneck is the cost of money. The average 12-month preferential mortgage rate is about 10.6% (the 12-month deposit rate is about 7.0%). Credit grew 11.6% over nine months while deposits grew 9.8%, the third year in a row that funding has lagged lending. September inflation reached 5.08%, above the State Bank’s 4.5% ceiling. According to press reports CBRE cites, the authorities raised the share of short-term funds allowed for medium- and long-term lending to 40% (June), counted State Treasury deposits at 50% in the loan-to-deposit calculation (August) and lifted the lending ceiling relative to deposits to 95% (early October).
Policy is pulling two ways: supporting growth and curbing speculation. Social housing is a priority (a target of 1 million units by 2030, a VND 120 trillion credit package, an income cap raised to VND 25 million a month), and together with industrial parks it is excluded from the 2026 real estate credit limits of 25 banks; tourism and resort loans are also left out of real estate credit growth. An urgent credit package of more than VND 750 trillion is earmarked for 18 strategic infrastructure projects. On the speculation side, the report notes groundwork for a property tax: a digital property ID, all transactions through banks, and a proposed tax on vacant homes or short-hold resales (not yet in force).
How to read it: strong growth and foreign capital show long-term demand is intact, but a 10.6% mortgage rate is the main reason buyers held back in Q3. We covered the rate backdrop in high loan interest rates in Vietnam (2026).
Graphic: Realtique · Data: CBRE Vietnam, Q3 2026 market report (asking prices, not transaction prices)
Apartments in Q3 2026: New Supply Halves, Sales Fall Even Faster
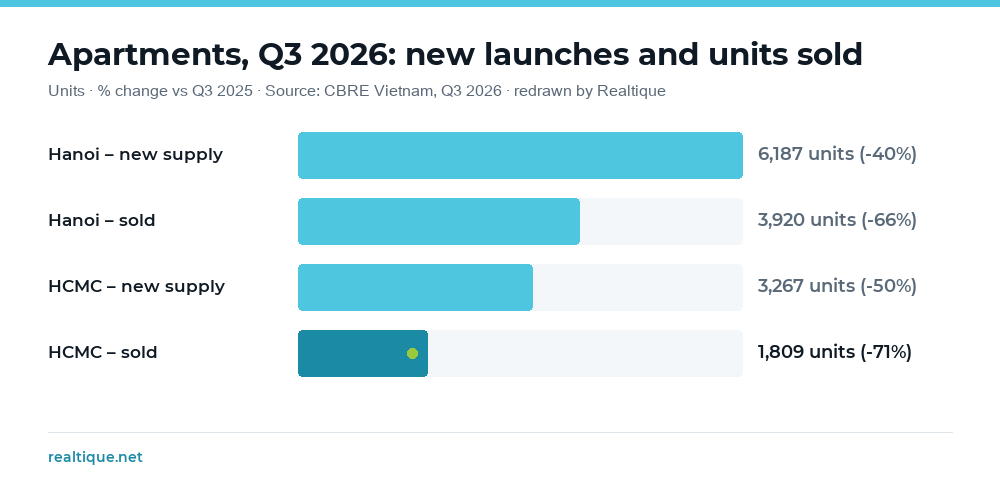
In both big cities, new launches and units sold were far below Q3 2025:
| Apartments, Q3 2026 | Hanoi* | HCMC** |
|---|---|---|
| New supply | 6,187 units (-40%) | 3,267 units (-50%) |
| Units sold | 3,920 units (-66%) | 1,809 units (-71%) |
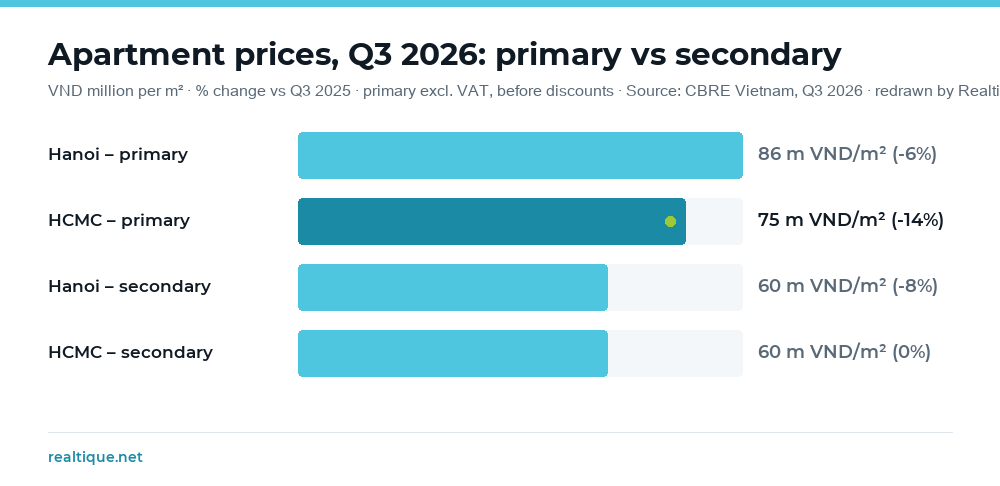
| Primary price | VND 86m/m² (-9% QoQ; -6% YoY) | VND 75m/m² (-2%; -14%) |
| Secondary price (asking) | VND 60m/m² (-5%; -8%) | VND 60m/m² (-4%; 0%) |
On the price rows, the two figures in brackets are QoQ then YoY (vs Q3 2025); the other rows are YoY. * Hanoi includes the large townships in Van Giang, Hung Yen (Ecopark, VOCP2, VOCP3, Sunshine Legend City, Alluvia City). ** From 2026 HCMC covers former HCMC, Binh Duong and Ba Ria – Vung Tau. Primary prices are asking prices excluding VAT and maintenance fees, before discounts.
The notable point is that units sold fell more than new supply (-71% vs -50% in HCMC, -66% vs -40% in Hanoi): buyers stepped back faster than developers cut launches. CBRE puts Hanoi’s Q3 apartment absorption at 63% (66% year to date); for HCMC, Realtique’s own division of the two figures above (1,809 / 3,267) gives roughly 55%. In HCMC the first two quarters of 2026 were the strongest launch period in the data series CBRE shows since 2023, so the Q3 pullback is more visible.
Realtique’s reading: when sales fall deeper than launches, developers tend to hold list prices and add payment support (longer schedules, interest support) rather than cut prices outright. When comparing projects, compare total cost after incentives, not only the list price.
Graphic: Realtique · Data: CBRE Vietnam, Q3 2026 market report (asking prices, not transaction prices)
HCMC Primary Price From VND 92 to 75 Million/m²: Reading the Number Correctly
The average primary price of an HCMC apartment was VND 92 million/m² in Q4 2025 and VND 75 million/m² in Q3 2026. But the two figures are not like-for-like: 92 million is former HCMC, while from 2026 CBRE adds Binh Duong and Ba Ria – Vung Tau, where price levels are lower. CBRE’s Q2 report put 79% of H1 2026 apartment supply in the new HCMC in former Binh Duong (see our Q2 2026 market report), so the basket of projects has changed. The drop from a changed basket and the drop from a weaker market arrive together; the report does not separate them.
In the secondary market the HCMC asking price is VND 60 million/m²: down 4% on Q2 and flat year on year. Hanoi is also at VND 60 million/m² but down 8% year on year, its first annual decline after two years of steady gains. Secondary asking prices in the two cities are converging on one level, while Hanoi’s primary price (VND 86 million) remains about 15% above HCMC’s (VND 75 million).
How to read it: VND 75 million/m² is the average of a wide basket under the new boundary, not the price list of any single project. Inner-city projects remain at a much higher level, and an asking price is before discounts, so the price actually paid after incentives may differ.
Graphic: Realtique · Data: CBRE Vietnam, Q3 2026 market report (asking prices, not transaction prices)
Landed Property: Hanoi Prices Rise on Slow Sales, HCMC Sells Better at Lower Prices
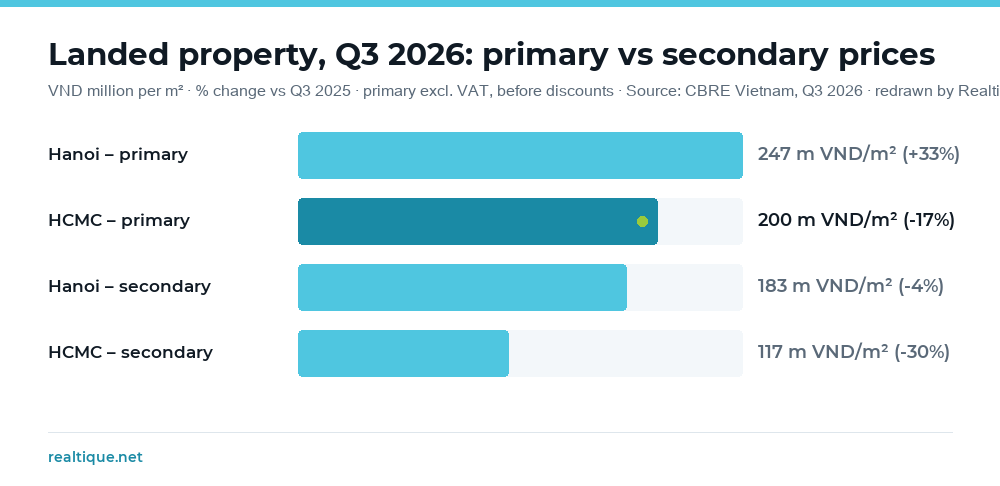
The two cities moved in opposite directions in landed property (townhouses, villas, project land):
| Landed property, Q3 2026 | Hanoi* | HCMC** |
|---|---|---|
| New supply | 1,517 units (+144%) | 30 units (-92%) |
| Units sold | 505 units (-21%) | 935 units (+226%) |
| Primary price | VND 247m/m² (+18% QoQ; +33% YoY) | VND 200m/m² (-4%; -17%) |
| Secondary price (asking) | VND 183m/m² (-6%; -4%) | VND 117m/m² (-6%; -30%) |
On the price rows, the two figures in brackets are QoQ then YoY (vs Q3 2025); the other rows are YoY. * and ** as in the apartment table above.
Hanoi: new launches pushed the primary price to VND 247 million/m², yet only 505 units sold; Q3 landed absorption was 33% (55% year to date). The market is testing higher price points and buyers have not followed.
HCMC: only 30 new units launched in Q3 but 935 sold, mostly stock from the large Q4 2025 launch wave. The primary price fell 17% year on year and the secondary price 30%, and CBRE says the decline reflects the provincial merger (a changed statistical boundary) as well as a slow market. Read HCMC landed property as a trend and do not treat the 30% drop as a precise figure.
Graphic: Realtique · Data: CBRE Vietnam, Q3 2026 market report (asking prices, not transaction prices)
Forecast 2026–2028: Ample Supply in Hanoi, a More Cautious HCMC
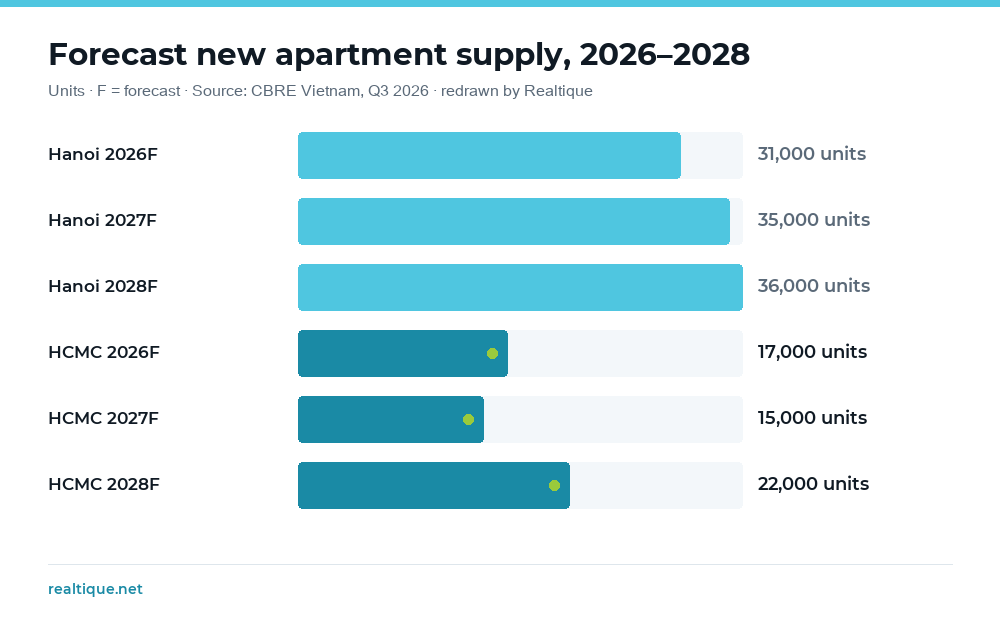
CBRE forecasts new supply as follows (the columns labelled on the report’s charts):
| Forecast new supply | 2026F | 2027F | 2028F |
|---|---|---|---|
| Hanoi apartments | 31,000 | 35,000 | 36,000 |
| HCMC apartments | 17,000 | 15,000 | 22,000 |
| Hanoi landed | 5,000 | 7,000 | 7,000 |
| HCMC landed | 4,000 | 3,000 | 5,000 |
In short: new apartment supply in HCMC is about half of Hanoi’s each year, so competition between projects is lighter in HCMC. On prices, CBRE’s forecast lines suggest HCMC apartment prices flat to lower than 2025 (primary VND 84 million/m², secondary VND 62 million/m², on a former-HCMC basis) while Hanoi runs above 2025 (primary VND 78 million/m², secondary VND 62 million/m²). This is a reading of the forecast lines; the report does not print figures for each year. CBRE’s own headline states the condition: interest rates remain the key to the market’s direction.
Graphic: Realtique · Data: CBRE Vietnam, Q3 2026 market report (asking prices, not transaction prices)
Social Housing: More Than 900,000 Units by 2030, With HCMC the Largest Target
Resolution 303/NQ-CP (30 September 2026) sets 2026–2030 social housing targets for nine localities: more than 900,000 units in total, about 709,000 units for sale and lease-to-own and 191,000 rental units. HCMC has the largest target, followed by Bac Ninh and Hanoi. The accompanying measures: specific targets by type, a push for rental housing, parallel handling of investment, land, planning, construction and environmental approvals, and digital applications with e-lottery allocation.
For buyers of mid- and high-end apartments the direct effect is small because the segments differ. The indirect effect is that credit and procedures are being prioritised for social housing and infrastructure, as noted in the macro section.
Realtique's Reading: Q3 2026 for Three Types of Buyer
1. Buyers who will live in the unit. Sales falling deeper than launches, plus a 10.6% mortgage rate, give buyers more time and more room to negotiate than in 2025. Compare list prices against total cost after incentives across projects in the same area, since CBRE’s asking prices are before discounts and a longer payment schedule can matter more than a few percent of price.
2. Investors. The forecast suggests HCMC apartment prices are unlikely to rise fast in the short term, so returns are better pegged to rental income and a longer holding period than to price gains. Avoid high leverage while mortgage rates sit at 10.6%, and watch the proposed tax on vacant homes and short-hold resales. Landlords should know the tax threshold in rental income tax in Vietnam (2026).
3. Foreign buyers and overseas Vietnamese. Foreigners may hold apartments in projects on the approved list, up to 30% of units per building, for 50 years with the option to renew (see can foreigners buy property in Vietnam and the 30% quota explained). Overseas Vietnamese who still hold Vietnamese citizenship buy as domestic citizens and do not count toward the quota. Remember that VND 75 million/m² is a wide average under the new boundary; compare prices project by project rather than by the city figure.
For the same quarter’s view from asking prices and a broker survey, see Ho Chi Minh City property market Q3 2026; for where the market sits in the cycle, is HCMC real estate entering its 2026 recovery cycle? and our Q2 2026 report for comparison.
Frequently Asked Questions
What are condo prices in Ho Chi Minh City in Q3 2026?
The average primary price is about VND 75 million/m² (excluding VAT, before discounts), down 2% on Q2 and 14% year on year. The secondary asking price is about VND 60 million/m². From 2026, CBRE’s HCMC figures include Binh Duong and Ba Ria – Vung Tau, so they are not like-for-like with 2025.
Is the HCMC apartment market rising or falling?
Q3 2026 was quiet: 3,267 new units launched (-50% year on year) and 1,809 units sold (-71%). The primary price fell and the secondary price was flat year on year. A mortgage rate near 10.6% is the main barrier.
Why did the HCMC primary price fall from VND 92 to 75 million/m²?
Two effects act together: the statistical boundary from 2026 adds Binh Duong and Ba Ria – Vung Tau (lower price levels), and the market weakened, with launches and prices both falling. The report does not separate the two, so the 14% drop should not be read as a price cut on one fixed basket of projects.
What is the mortgage rate in Vietnam now?
The average 12-month preferential mortgage rate was about 10.6% a year in September 2026, against a 12-month deposit rate of about 7.0% (a survey of selected commercial banks, per CBRE). September inflation was 5.08%, above the State Bank’s 4.5% ceiling.
Which is cheaper, Hanoi or HCMC apartments?
In CBRE’s Q3 2026 data the HCMC primary price (VND 75 million/m²) is below Hanoi’s (VND 86 million/m²); secondary asking prices are both about VND 60 million/m². Hanoi has nearly twice the new supply (6,187 vs 3,267 units), and Hanoi’s figures include large townships in Hung Yen.
Can foreigners buy an apartment in Ho Chi Minh City?
Yes, but only apartments and housing in projects on the approved ownership list, up to 30% of units per building, for 50 years with the option to renew. Overseas Vietnamese who still hold Vietnamese citizenship buy as domestic citizens. Check the remaining quota of each building before paying a deposit.
⚠️ Data source: CBRE Vietnam, Q3 2026 Vietnam Real Estate Market Insights (October 2026); all rights belong to CBRE. Primary prices are asking prices excluding VAT and maintenance fees, before discounts; secondary prices are asking prices adjusted to exclude VAT and maintenance fees; both are not completed transaction prices. Hanoi figures include large townships in Hung Yen; HCMC figures from 2026 include former HCMC, Binh Duong and Ba Ria – Vung Tau. Charts are redrawn by Realtique from the report’s figures; the commentary is Realtique’s view. This article is not investment advice.
Ho Chi Minh City Property Market Q3 2026: Asking Prices Slide, Apartments Hold Firm
Read more →High Loan Interest Rates in Vietnam (2026): What Home Buyers Should Do
Read more →Can Foreigners Buy Property in Vietnam? (2026 Rules & Process)
Read more →Vietnam’s 30% Foreign Ownership Quota Explained (2026)
Read more →Want the real price of the project you are eyeing?
An asking price in a report is before discounts. Send Realtique the project and unit type: we will check recent transactions, compare payment schedules across projects and confirm the foreign-ownership quota if you need it, before you make an offer or pay a deposit.
📞 Hotline: +84 866 810 689
KC Pham
KC Pham advises foreign buyers, overseas Vietnamese and investors on apartments in Ho Chi Minh City — reading market data with clients, comparing new-launch prices with nearby secondary prices, and confirming payment schedules and the foreign-ownership quota before any deposit.