Ho Chi Minh City Property Market Q3 2026: Asking Prices Slide, Apartments Hold Firm
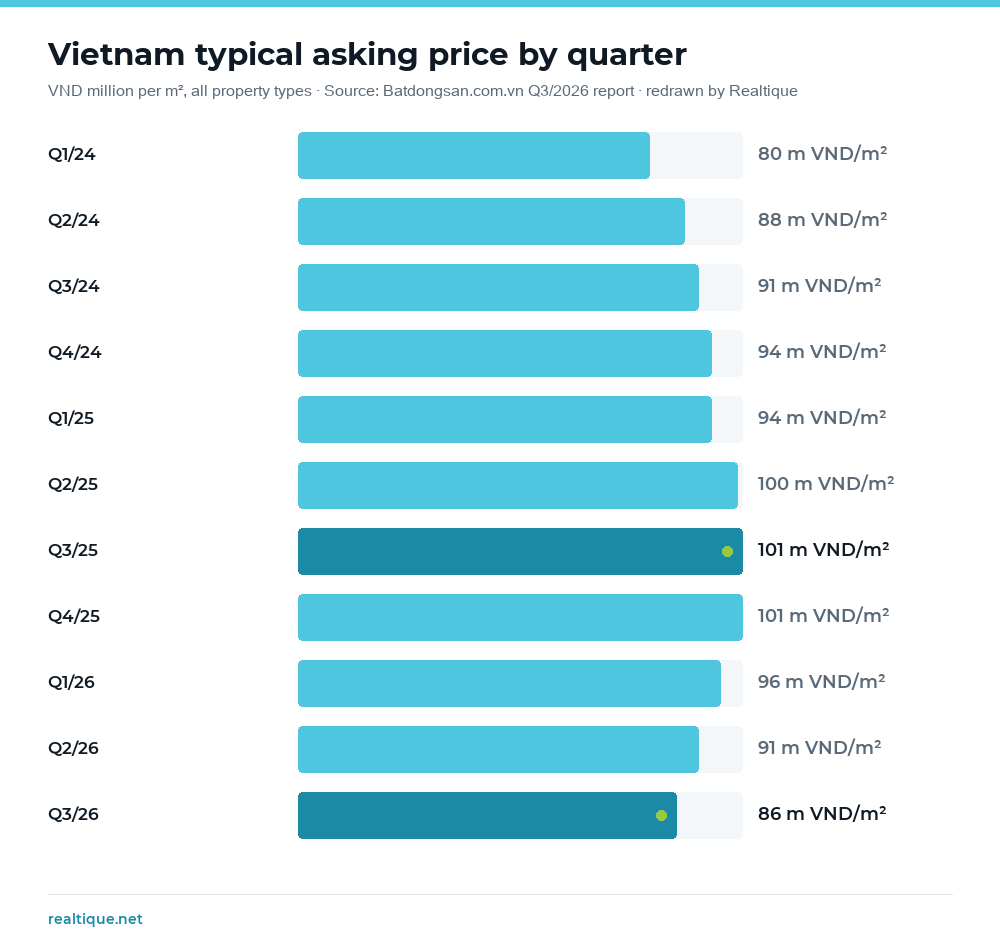
Short answer: in Q3 2026 Vietnam’s property market moved in two directions. Asking prices kept falling: the typical nationwide level dropped to VND 86 million/m², a third straight quarterly decline from the VND 101 million peak. Yet transactions edged up from Q2. In Ho Chi Minh City, apartments held almost flat at VND 69 million/m² (−1%) and remained the most searched property type, while buyers shifted toward new launches and toward former Binh Duong.
The numbers come from Batdongsan.com.vn’s Vietnam Real Estate Market Overview Q3 2026, built on listing data and a survey of 530 brokers. Realtique has read it from the point of view of an apartment buyer in Ho Chi Minh City, redrawn the charts and cross-checked them against the projects we follow. The single most important caveat: these are asking prices set by sellers, not completed transaction prices.
Vietnam Property Market Q3 2026 — 4 Key Numbers
Table of Contents
Nationwide: Asking Prices Down Three Quarters in a Row, Transactions Edging Up
According to Batdongsan.com.vn, the typical nationwide asking price (all property types) climbed from VND 80 million/m² in early 2024 to a peak of VND 101 million/m² in Q3 and Q4 2025. In 2026 it turned: VND 96 million (Q1), VND 91 million (Q2) and VND 86 million/m² (Q3), about 15% below the peak. Typical asking rents barely moved, at around VND 17–18 million a month.
What changed in Q3 was transaction activity. In the survey of 530 brokers, the share reporting that deals had fallen sharply (by more than 50%) eased to 48% from 50% in Q2. About 30% reported a moderate fall, 17% stable and 5% higher. The market is still weak, but the survey has stopped getting worse.
Sentiment remains guarded: 63% of brokers described Q3 as cautious, 17% negative, 12% neutral and only 8% optimistic.
How to read it: falling asking prices mostly reflect resale sellers lowering expectations to get deals done. They do not mean every unit is 15% cheaper. For where the market sits in the cycle, see has HCMC real estate entered its recovery cycle.
Graphic: Realtique · Data: Batdongsan.com.vn, Vietnam Real Estate Market Overview Q3 2026
Apartments Lead, and Buyers Are Moving to New Launches
Apartments are recovering better than any other type, in both search interest and transactions:
- Search interest: apartments took 37% of all for-sale search interest nationwide in Q2 and Q3 2026, the highest of any type (32–34% through 2024). Land took 24% and townhouses 21%.
- Transactions: 40% of brokers reported a sharp fall in apartment deals, the lowest of any type. The figure was 48% for villas, 50% for townhouses, 51% for land plots and 57% for street-front houses.
- Next six months: 36% of brokers picked apartments as the most promising type, ahead of townhouses (32%), villas (13%), street-front houses and land (9% each).
The clearest shift is from resale toward new launches (newly released apartments and villas). Their share of search interest rose from 11% in December 2025 to 28% in August–September 2026. The reason lies in what is holding buyers back:
| Biggest obstacle for buyers right now | % of brokers |
|---|---|
| Mortgage rates still high | 46% |
| Worries about policy and planning changes | 32% |
| Limited cash flow | 25% |
| Prices high relative to affordability | 18% |
| No suitable product found | 3% |
| Project legal status | 3% |
The top three are all about cash flow, and new launches answer exactly that: developers spread payments over a long schedule and offer interest support or principal grace periods, so buyers do not need to raise a large sum up front as they would for a resale unit.
Ho Chi Minh City: Asking Prices by Property Type, Q3 2026
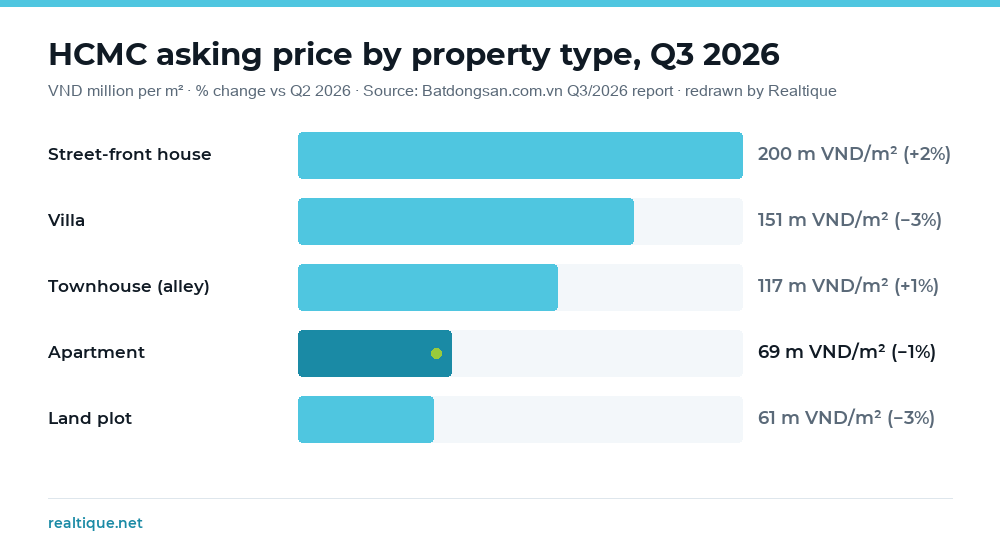
In Ho Chi Minh City, asking prices were flat or slightly lower across most types:
| Type (HCMC) | Asking price Q3 2026 | vs Q2 2026 | Share of search interest |
|---|---|---|---|
| Street-front house | VND 200m/m² | +2% | 11% |
| Villa | VND 151m/m² | −3% | 6% |
| Townhouse (alley) | VND 117m/m² | +1% | 31% |
| Apartment | VND 69m/m² | −1% | 38% (Q2: 35%) |
| Land | VND 61m/m² | −3% | 14% |
HCMC apartment asking prices rose steadily from VND 48 million/m² in early 2024 to VND 70 million/m² in Q2 2026, and gave back only 1% in Q3, the best price resilience of any type while the national figure was falling about 5% a quarter.
Townhouses held steady. The three most searched districts, Binh Thanh, Thu Duc and Go Vap, all ticked up: Binh Thanh VND 151 million/m² (+1%), Go Vap VND 123 million/m² (+1%), Thu Duc VND 93 million/m² (+2%). The report flags a supply-demand mismatch in the old city: homes under VND 5 billion draw 37% of interest but only 22% of listings, while VND 5–10 billion homes make up 59% of listings but only 45% of interest. Most townhouse buyers are either waiting (35%) or haggling for a lower price (24%); only 19% close quickly when the price is right.
Graphic: Realtique · Data: Batdongsan.com.vn, Vietnam Real Estate Market Overview Q3 2026
Infrastructure Is Widening the Price Gap
Metro Line 1 gives the clearest evidence. Asking prices for apartments within 1 km of Metro Line 1 and the Hanoi Highway (projects first listed before 2019 only) rose from VND 30.6 million/m² in 2016 to VND 51.4 million in 2024, VND 67 million in 2025 (+30%, the year the line opened) and VND 72.9 million/m² in 2026.
A price index (2018 = 100) shows the effect is stronger away from the centre than in the core: Thu Duc apartments within 1 km of a station reach 230, the rest of HCMC away from stations 193, while the core (Districts 1, 3, 4 and Binh Thanh), even within 1 km of a station, sits at only 183. The full Metro Line 1 and TOD analysis is in what is TOD, and the foreign-buyer angle in HCMC metro and property value.
Main infrastructure projects under way, as compiled by Batdongsan.com.vn (dates are targets and may change):
| Project | Length | Status per the report |
|---|---|---|
| Ring Road 3 | ~76 km | About 81% complete; the 14.7 km eastern section targets opening in Nov 2026, some sections pushed to 2027 |
| Ring Road 4 | ~207 km | 2 component projects started; the rest in land clearance and PPP procedures |
| HCMC – Long Thanh – Dau Giay Expressway (widening) | ~22 km | About 73% of plan, accelerated for Long Thanh Airport |
| Metro Line 2 Ben Thanh – Tham Luong | ~11 km | Started Jan 2026, all land handed over |
| Metro Line 2 Ben Thanh – Thu Thiem section | ~6 km | Started Apr 2026, operation targeted for 2030 |
| Thu Thiem – Long Thanh Metro | ~42 km | Procedures being completed, rollout expected in 2026 |
| Metro Line 6 Tan Son Nhat – Phu Huu | ~23 km | Groundbreaking expected Dec 2026 |
| Metro Line 1 extension Suoi Tien – Binh Duong New City | ~32 km | Groundbreaking expected Dec 2026 |
| Ben Thanh – Can Gio Metro | ~54 km | Land clearance under way, operation targeted for 2028 |
Reference Prices for New Projects Along the Infrastructure Corridors
The report lists new apartment supply spreading along the infrastructure corridors, with reference prices. These are the projects Realtique follows and has covered in detail:
| Project | Developer | Area | Reference price* |
|---|---|---|---|
| SkySOLIS | SkyWorld (Malaysia) | Former Binh Duong – Thuan An | VND 47m/m² |
| Norton Park | Gamuda Land | Former Binh Duong – Thuan An | VND 63m/m² |
| Nexus Zone | Masterise Homes | East – former District 2 | VND 124m/m² |
| Gladia Heights | Khang Dien & Keppel | East – Vo Chi Cong | VND 83m/m² |
| Imperia Sensa Park | MIK Group | East – Vo Chi Cong | VND 87m/m² |
| The Westique Residences | TD ICONIC (VCRE) | West – Binh Tan | VND 95m/m² |
| Vinhomes Saigon Park | Vinhomes | North – Hoc Mon | VND 54m/m² |
* Reference prices per Batdongsan.com.vn Q3 2026, not developers’ official price lists; they may use a different area basis (gross or net). Norton Park, for example: the developer price list Realtique holds is about VND 66 million/m² on gross area (see Norton Park price and payment plans).
The overall picture: former Binh Duong sits at VND 43–63 million/m², the East (former District 2, Vo Chi Cong) at VND 83–124 million, the West at VND 69–95 million and the North around VND 54 million. A gap of nearly two times between the satellite areas and the East explains why interest is moving outward.
SkySOLIS
~VND 47m/m²*View project →Norton Park
~VND 63m/m²*View project →Nexus Zone
~VND 124m/m²*View project →Gladia Heights
~VND 83m/m²*View project →Imperia Sensa Park
~VND 87m/m²*View project →The Westique Residences
~VND 95m/m²*View project →HCMC Buyers Are Looking at the Satellite Areas
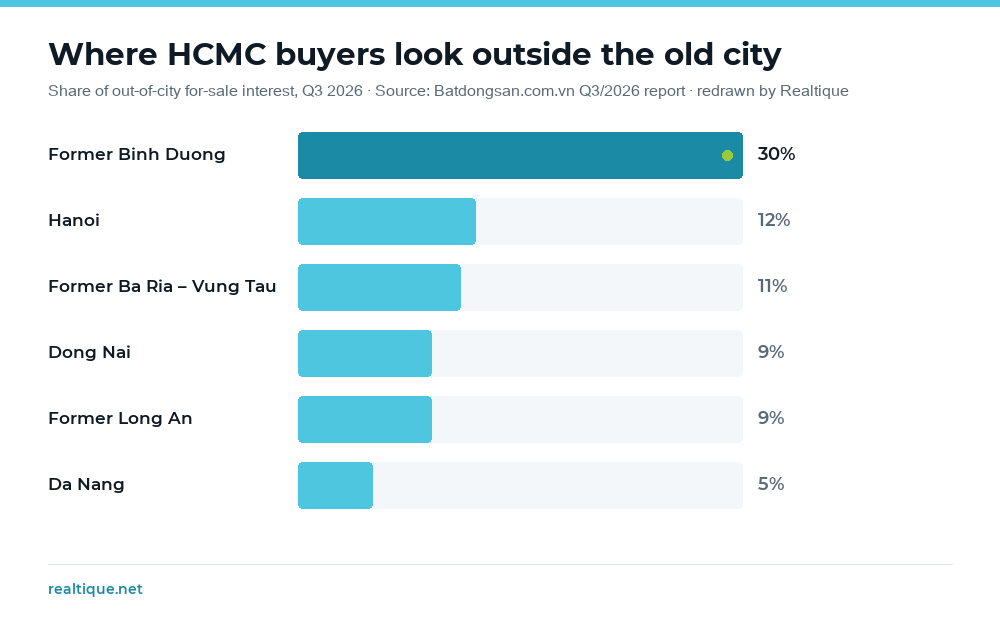
Of the for-sale search interest that HCMC residents direct outside the old city, former Binh Duong rose from 9% (Q1 2024) to 30% (Q3 2026), now the top destination. Hanoi fell from 41% to 12%. Former Ba Ria – Vung Tau takes 11%, Dong Nai and former Long An 9% each, Da Nang 5%.
What they search for differs by area. In former Binh Duong, apartments make up 38% of HCMC residents’ interest (31% in early 2024). In Ba Ria – Vung Tau, Long An and Dong Nai, HCMC buyers still mainly look at land (53–62%).
Projects such as Norton Park and SkySOLIS on National Route 13 are positioned for this flow. For foreign buyers considering the area, see the Binh Duong New City guide.
Graphic: Realtique · Data: Batdongsan.com.vn, Vietnam Real Estate Market Overview Q3 2026
Street-Front Rentals: District 2 Has the Best Yield in the Core
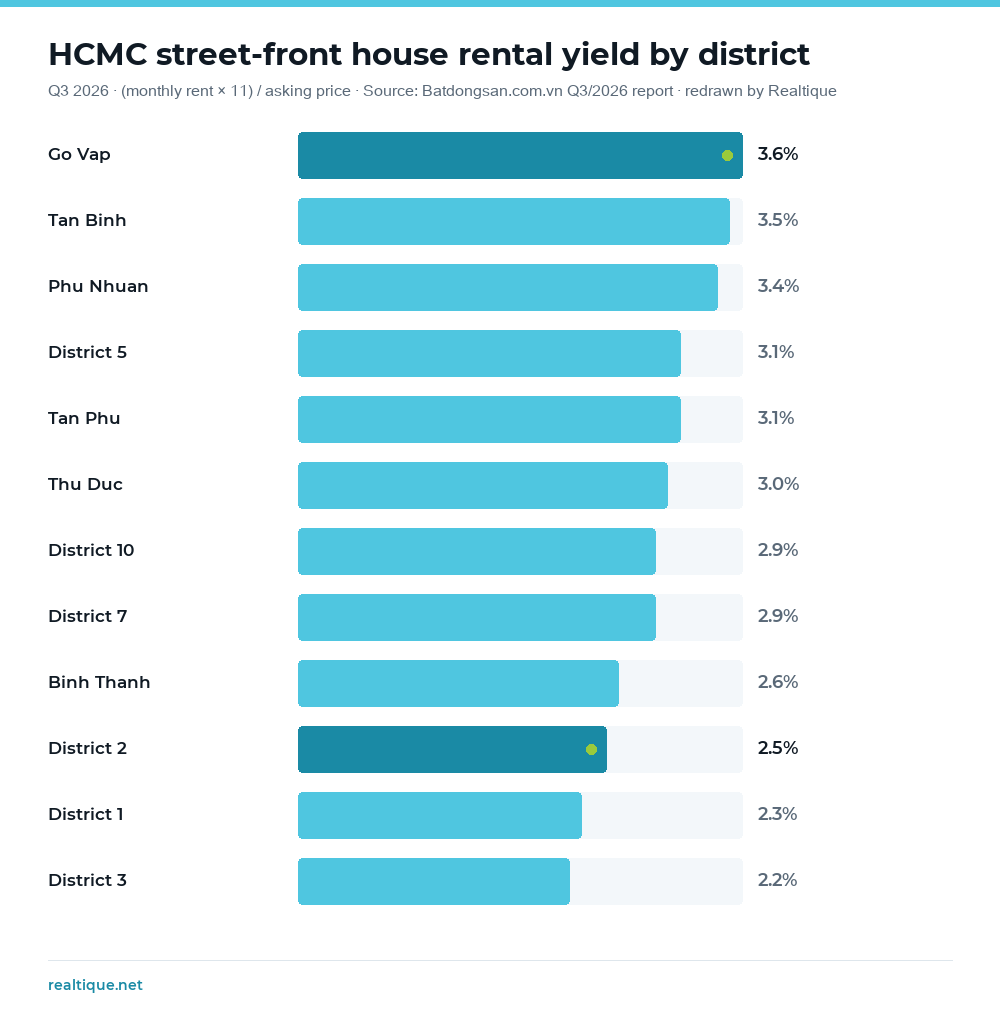
Districts 1, 2 and 3 continue to lead demand for street-front rentals (16%, 9% and 8% of rental search interest over the first three quarters of 2026). Street-front rental yields (monthly rent × 11 divided by asking price) improved in both groups: the centre from 1.9% in early 2024 to 2.3%, the inner suburbs to 3.1%.
Among the three central districts, District 2 yields the most, 2.5%, because street-front asking prices are about VND 249 million/m², half of District 1 (VND 500 million) and below District 3 (VND 420 million). In the inner suburbs, Go Vap leads at 3.6% with asking prices around VND 160 million/m².
Landlords with several units should check the tax threshold: total rental revenue above VND 1 billion a year becomes taxable, explained in rental income tax in Vietnam 2026.
Graphic: Realtique · Data: Batdongsan.com.vn, Vietnam Real Estate Market Overview Q3 2026
Hanoi and Da Nang in Brief
Hanoi: the typical asking price eased from VND 194 million/m² (Q4 2025) to 189, 175 and then VND 165 million/m² in Q3 2026, but the pace of decline has slowed. The share of brokers reporting sharply lower deals fell from 59% (Q2) to 52%. Apartments now take 52% of search interest (39% at the start of the year); apartment asking prices are VND 82 million/m² (−5%), land corrected the most (VND 69 million/m², −10%) and townhouses held at VND 252 million/m². Villas linked to new infrastructure in the satellite areas, especially Ha Dong, drew the most interest in that segment.
Da Nang: apartments are attracting more interest and holding value better than other types, helped by tourism and rental yields among the highest of Vietnam’s tourist cities; demand is concentrated in Son Tra, Ngu Hanh Son and Hai Chau. Land plots are correcting after a hot run. Street-front houses posted standout price growth over the past two years, led by Son Tra and Ngu Hanh Son.
Realtique's View: Reading Q3 2026 for Three Kinds of Buyer
1. Buying to live in. Q3 is a good moment to negotiate on resale: asking prices have eased for three quarters, 24% of townhouse buyers are haggling and sellers are more willing to listen. Compare the asking price with recent transactions in the same building and unit type before making an offer; the asking price is a ceiling, not the market level.
2. Investors. The price gap between areas with finished infrastructure and areas still waiting is real (an index of 230 against 193), but timelines can slip, as some Ring Road 3 sections have. With mortgage rates the top obstacle, favour new launches with long payment schedules over high leverage while you wait for infrastructure.
3. Foreign buyers and overseas Vietnamese. Apartments are, in practice, what foreigners can hold title to: projects on the approved list, up to 30% of units per building, a 50-year term that can be extended (see can foreigners buy property in Vietnam and the 30% quota explained). Q3 2026 shows they are also the type holding value best in Ho Chi Minh City. Overseas Vietnamese who still hold Vietnamese citizenship buy as locals, outside the quota.
For the previous quarter, see the Vietnam real estate market Q2 2026 outlook (supply and primary price data).
Frequently Asked Questions
How is the Ho Chi Minh City property market doing in Q3 2026?
Asking prices were flat or slightly lower: apartments VND 69 million/m² (−1% vs Q2), townhouses VND 117 million/m² (+1%), land VND 61 million/m² (−3%). Apartments drew the most interest (38%). Buyers are moving toward new launches and former Binh Duong (Batdongsan.com.vn, Q3 2026).
Are property prices in Vietnam rising or falling?
The typical nationwide asking price fell for three straight quarters, from VND 101 million/m² (Q3–Q4 2025) to VND 86 million/m² in Q3 2026. These are asking prices, not transaction prices, and most of the decline is in resale stock. HCMC apartments were almost flat.
What is the average apartment price in Ho Chi Minh City in 2026?
The typical apartment asking price in HCMC was about VND 69 million/m² in Q3 2026, down 1% from Q2 (VND 70 million). New projects along the infrastructure corridors are listed from about VND 43–63 million/m² in former Binh Duong to VND 83–124 million/m² in the East.
Why are buyers moving to new launches?
Because the biggest obstacles are mortgage rates (46% of brokers), policy and planning worries (32%) and limited cash flow (25%). New launches offer long payment schedules and interest support. Their share of search interest rose from 11% (Dec 2025) to 28% (Sept 2026).
Which HCMC districts have the best street-front rental yield?
Among the central districts, District 2 has the highest street-front yield (2.5%) because asking prices are about VND 249 million/m², far below District 1 (VND 500 million) and District 3 (VND 420 million). In the inner suburbs, Go Vap leads at 3.6%.
What property should a foreigner buy in Ho Chi Minh City?
Foreigners can hold title to homes in commercial housing projects on the approved list, up to 30% of apartments per building, for 50 years with extension; in practice that means apartments. In Q3 2026 apartments were also the type holding value best in HCMC.
⚠️ Data source: Batdongsan.com.vn, Vietnam Real Estate Market Overview Q3 2026 (listing data and a survey of 530 brokers in Q3 2026). Prices in this article are typical asking prices, not completed transaction prices; project reference prices are not developers’ official price lists. Charts are redrawn by Realtique from the report’s figures; the commentary is Realtique’s view. Infrastructure dates are targets and may change. This article is not investment advice.
Want the real price of the unit you are eyeing?
An asking price is only a ceiling. Send Realtique the project and unit type: we will check recent transactions, compare payment schedules across new launches and confirm the foreign-ownership quota if you need it, before you make an offer or pay a deposit.
📞 Hotline: +84 866 810 689
Grace Le
Grace Le advises foreign buyers and overseas Vietnamese on apartments across Ho Chi Minh City and former Binh Duong: checking asking prices against recent transactions, comparing payment schedules between new launches, and confirming the remaining foreign-ownership quota before any deposit.